

How much was Bitcoin worth in 2020?
Cryptocurrency and Bitcoin in 2020: A Technical History of Scarcity, Shock, and Decentralized Finance
The history of cryptocurrency and Bitcoin for the year 2020 cannot be understood as a simple price story. It was a year in which a young monetary network, born from cypherpunk skepticism and cryptographic experimentation, was forced to interact with global macro stress, institutional liquidity, decentralized finance, and a pandemic-driven monetary response unlike anything seen in modern economic history. By 2020, Bitcoin was no longer merely an obscure digital cash experiment discussed on niche forums. It had become a live stress test for ideas about trust, scarcity, settlement, censorship resistance, and programmable money.
At the beginning of the year, the crypto market was still recovering from the excesses and collapses of prior cycles. Bitcoin was trading in a range that many veteran observers considered mature, but the underlying infrastructure had changed significantly since the 2017 peak. Segregated Witness had been active for years, the Lightning Network was maturing, Ethereum was preparing for a multi-year transition to proof-of-stake, and decentralized finance was beginning to transform smart contracts from theoretical platforms into active financial markets. By December 2020, the conversation had shifted from whether cryptocurrency could survive its own volatility to whether it could become a settlement layer for global digital finance.
Why 2020 Became a Turning Point
2020 mattered because it compressed several historical forces into a single year. First, Bitcoin experienced its third halving, reducing the block subsidy from 12.5 BTC to 6.25 BTC and reinforcing the protocol’s fixed issuance schedule. Second, the global pandemic triggered emergency monetary expansion, pushing investors to search for alternative monetary assets. Third, decentralized finance exploded into mainstream crypto culture, creating new markets for lending, borrowing, automated liquidity provision, and yield-bearing tokens. Fourth, institutional participation became more visible, with public companies, payment firms, and regulated custodians beginning to treat Bitcoin as a legitimate treasury asset.
The result was a year of extreme contradictions. Bitcoin crashed violently in March alongside equities, commodities, and high-yield assets, suggesting that crypto was still a risk asset correlated with liquidity conditions. Yet by the end of the year, it outperformed most major asset classes and became a focal point for narratives around monetary debasement and digital scarcity. The history of cryptocurrency in 2020 is therefore not only a history of technological development, but also a history of market psychology, monetary theory, and the tension between decentralization and institutional adoption.
Cypherpunk Roots Behind the 2020 Market
To understand 2020, one must return to the intellectual lineage that made cryptocurrency possible. The movement did not begin with Bitcoin. It emerged from decades of work on digital cash, cryptographic privacy, hashcash proof-of-work, b-money, Bit Gold, and cypherpunk mailing list debates about surveillance, state power, and trusted third parties. The central insight was not that money could be digital, because banks had already achieved that. The insight was that digital money could be designed to operate without a central validator, using cryptography and economic incentives instead of institutional permission.
A purely peer-to-peer version of electronic cash would allow online payments to be sent directly from one party to another without going through a financial institution.
That sentence from the Bitcoin whitepaper remained philosophically central in 2020. While markets focused on price, developers and long-time community members continued to emphasize the original problem: how to prevent double-spending without reintroducing a trusted intermediary. Bitcoin’s answer was a decentralized ledger secured by proof-of-work, timestamped blocks, and the longest-chain rule. Ethereum extended the model by making the ledger programmable, allowing contracts to manage assets, enforce conditions, and compose into more complex financial systems. By 2020, these two architectures represented distinct but related paths: Bitcoin as a conservative monetary settlement network, Ethereum as an experimental programmable settlement layer.
Bitcoin’s Technical Architecture in 2020
By 2020, Bitcoin’s technical design was deliberately conservative compared with newer smart contract platforms. Its base layer prioritized predictability, auditability, and resistance to consensus failure. The network continued to rely on an unspent transaction output model, where value is tracked as discrete UTXOs rather than account balances. This model gives Bitcoin strong privacy potential when used carefully, simplifies parallel verification, and makes transaction validity easier to reason about at the protocol level.
- The UTXO model allowed wallets and nodes to verify value without reconstructing a global account state.
- Bitcoin Script remained intentionally limited, favoring simple and auditable spending conditions over complex programmability.
- Segregated Witness separated signature data from transaction structure, reducing malleability and improving block capacity efficiency.
- The Lightning Network provided a second-layer payment system built on hashed timelock contracts and multisignature funding channels.
- Full nodes remained essential for validating consensus rules, preserving decentralization against pressure from miners, exchanges, and large wallet providers.
Mining in 2020 was highly industrialized but still governed by the same core feedback loop: SHA-256 computational power competes for block rewards, while the difficulty adjustment aligns block production with available hash rate. This mechanism gave Bitcoin a form of autonomous monetary operations. No committee could decide to accelerate issuance or rescue a failing miner. The protocol responded only to accumulated proof-of-work and the passage of blocks. For supporters, this rigidity was the point. For critics, it was a limitation that would eventually constrain scalability or security.
The March 2020 Liquidity Shock
The first major test of the year arrived in March, when global markets entered a liquidity crisis following the rapid spread of the pandemic. Bitcoin, often described by enthusiasts as a hedge against systemic failure, initially behaved like a high-beta risk asset. As investors rushed to obtain cash, leveraged positions were unwound across exchanges, and correlations between crypto, equities, and commodities surged toward one. Bitcoin fell sharply from the low thousands to levels not seen since the prior bear market, exposing the fragility of exchange infrastructure, custody operations, and decentralized lending protocols under extreme volatility.
The crash also revealed technical weaknesses in decentralized finance. On Ethereum, sharp price moves caused liquidations in lending protocols, especially where oracle feeds, gas prices, and auction mechanisms could not keep pace with market disorder. In some cases, liquidators competed so aggressively that transactions failed or executed under unfavorable conditions, creating bad debt and forcing governance discussions around risk parameters. The episode was a reminder that smart contracts do not eliminate financial risk; they encode it into software, oracles, and incentive design.
For Bitcoin, March 2020 reinforced an important lesson: monetary networks are not isolated from macro liquidity. Even a fixed-supply asset can fall when market participants need to sell whatever is liquid. Yet the recovery that followed was equally instructive. As central banks expanded balance sheets and fiscal support increased, Bitcoin began to attract attention not only as a speculative instrument but also as a potential hedge against currency debasement. The technical network did not change during the crash, but the market’s interpretation of it began to evolve.
The Third Bitcoin Halving
The most structurally important Bitcoin event of 2020 was the third halving, which occurred at block 630,000 on May 11, 2020. The block reward decreased from 12.5 BTC to 6.25 BTC, cutting the rate at which new coins entered circulation. Unlike conventional monetary systems, where supply can respond to political or economic conditions, Bitcoin’s issuance schedule is enforced by consensus rules and cryptographic proof-of-work. The halving did not require a vote, a board decision, or an emergency intervention. It happened because the protocol reached a predetermined block height.
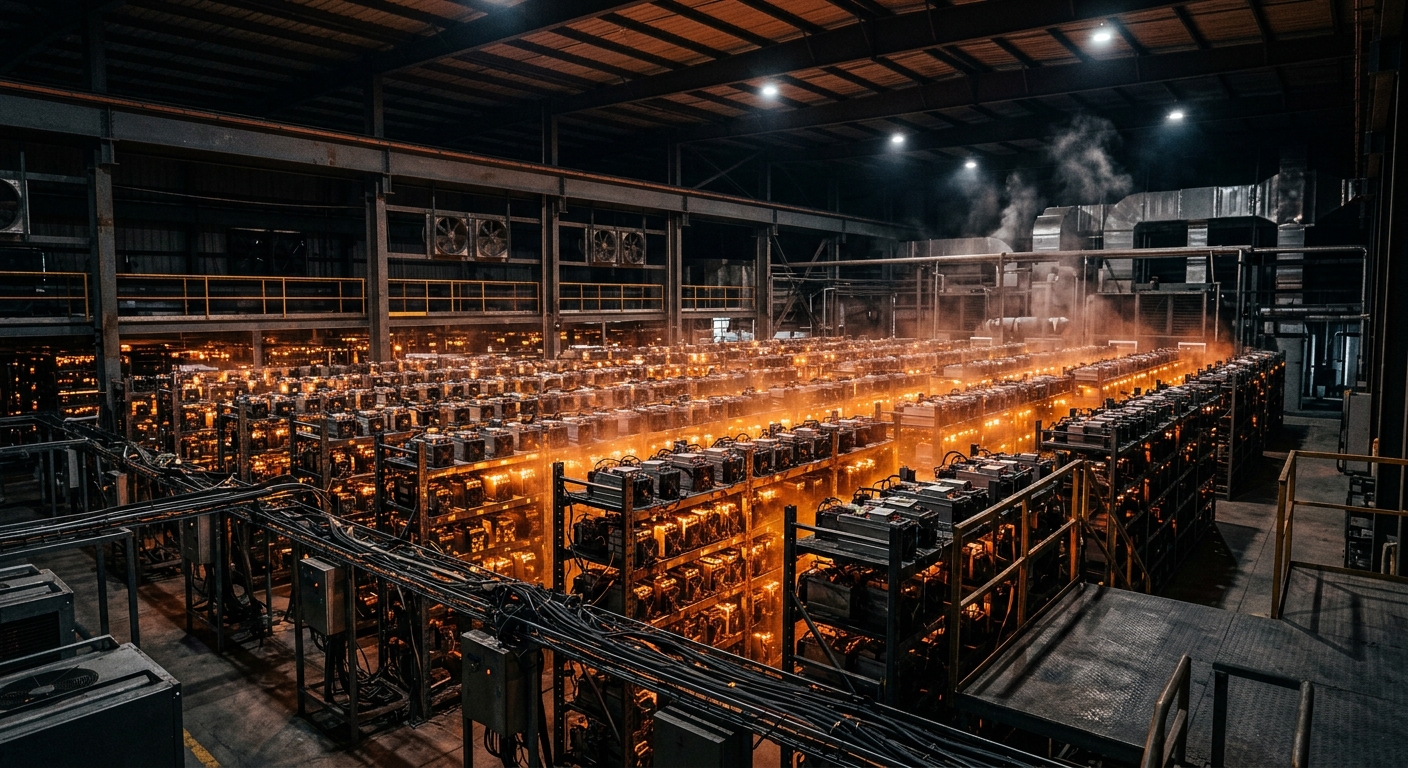
Technically, the halving affected miners first. Block revenue declined instantly, while hardware efficiency, electricity costs, and hash price determined which operations remained profitable. Some older equipment became uneconomic, leading to short-term hash rate volatility and regional migration of mining capacity. The difficulty adjustment then rebalanced the network, ensuring that block times remained close to ten minutes. This feedback loop was one of Bitcoin’s most elegant mechanisms: security expenditure could fluctuate, but the monetary schedule remained intact.
Forum reactions were mixed. Veteran users often warned newcomers not to treat the halving as an immediate price catalyst, arguing that markets could price in expected scarcity long before the event. Others focused on stock-to-flow models, miner revenue, and long-term monetary premium. Skeptics pointed out that previous halvings did not guarantee identical future outcomes, especially as market structure became more institutional. Still, the halving sharpened Bitcoin’s core narrative: a digital asset with a transparent supply curve, secured by energy and computation, and resistant to discretionary issuance.
DeFi Summer and the Programmable Money Explosion
If Bitcoin’s 2020 story centered on scarcity, Ethereum’s story centered on composability. The decentralized finance sector grew from a relatively small ecosystem of lending protocols and decentralized exchanges into a broad financial laboratory. The phrase DeFi summer captured the frenzy around liquidity mining, yield farming, automated market makers, governance tokens, and experimental capital efficiency strategies. What began as a niche movement among Ethereum developers and power users became one of the defining crypto narratives of the year.
The technical foundation of this expansion was simple but powerful. Smart contracts could hold assets, enforce rules, and interact with other contracts without requiring a centralized intermediary. Automated market makers replaced traditional order books with liquidity pools governed by mathematical formulas. The constant product model, commonly expressed as x times y equals k, allowed users to trade against a pool by adjusting the ratio of two assets. Prices emerged from reserve balances rather than from matched buy and sell orders. This design was less capital efficient than mature centralized exchanges, but it was permissionless, composable, and continuously available.
Lending protocols introduced algorithmic interest rates, overcollateralized borrowing, and liquidation mechanisms enforced by code. Liquidity mining added token incentives to bootstrap participation, turning users into stakeholders and creating reflexive loops between token price, liquidity, and protocol governance. Flash loans enabled uncollateralized borrowing within a single transaction, provided the funds were returned by the end of the atomic operation. This primitive was technically elegant but also controversial, because it allowed attackers to manipulate prices, exploit oracle weaknesses, and amplify vulnerabilities without committing large amounts of capital upfront.
The risks were substantial. Smart contract bugs, admin key compromises, oracle manipulation, governance attacks, and unsustainable yield models all appeared throughout the year. Yet the educational impact was enormous. DeFi forced participants to think carefully about custody, contract risk, collateralization ratios, liquidation incentives, and the difference between decentralization in theory and decentralization in practice. By the end of 2020, decentralized finance had become a permanent part of cryptocurrency history, not as a finished financial system, but as an open experimental environment for monetary software.
Ethereum’s Congestion and the Beacon Chain Launch
The surge in DeFi activity placed severe strain on Ethereum’s base layer. Gas fees rose sharply during periods of high demand, making small transactions expensive and pushing users toward layer-two concepts, alternative chains, and higher-risk yield strategies. The congestion was a sign of product-market fit, but it also exposed the limits of a proof-of-work blockchain whose security model and throughput had not yet been redesigned for global financial usage.
The response was not immediate scaling, but a long-term architectural transition. On December 1, 2020, the Ethereum Beacon Chain launched, marking the beginning of the proof-of-stake era. Phase 0 did not immediately replace the existing execution environment, but it introduced validator economics, staking deposits, slashing conditions, and a new coordination layer for future upgrades. Validators were required to lock 32 ETH, creating a security model based on capital at risk rather than specialized mining hardware.
This was one of the most technically ambitious undertakings in cryptocurrency history. Moving a live economic network from proof-of-work to proof-of-stake required careful coordination among client developers, node operators, exchanges, wallet providers, and smart contract teams. The Beacon Chain launch demonstrated that Ethereum could evolve through staged engineering rather than abrupt replacement. It also deepened the philosophical contrast between Bitcoin and Ethereum: Bitcoin favored minimal change to preserve monetary credibility, while Ethereum embraced iterative complexity to support programmable finance.
Stablecoins, Regulation, and Institutional Entry
Stablecoins became a crucial bridge between traditional finance and crypto markets in 2020. They provided settlement liquidity, collateral for decentralized finance, and a means for traders to move value without exiting to bank rails. The year saw increased scrutiny around reserve transparency, redemption rights, and regulatory classification, but it also saw stablecoins become more embedded in exchange ecosystems, payment experiments, and cross-border transfers.
Institutional participation accelerated in several ways. Public companies began allocating treasury capital to Bitcoin, payment companies announced support for crypto assets, and regulated custodians expanded services for digital assets. In the United States, regulatory guidance around bank custody and node operation suggested that traditional financial institutions could participate in crypto infrastructure without necessarily abandoning compliance requirements. These developments did not resolve the tension between permissionless networks and regulated intermediaries, but they made that tension impossible to ignore.
For Bitcoin, institutional entry changed the market structure. Large buyers tended to focus on custody, auditability, and long-term scarcity rather than cypherpunk ideology. For Ethereum, institutional interest was more complex, because smart contract platforms raised questions about securities law, governance, and the legal status of decentralized protocols. 2020 therefore set the stage for a decade-long conflict between open networks and regulatory frameworks.
Forum Culture and Early Community Reactions
The cultural history of cryptocurrency in 2020 was shaped by forums, chat rooms, developer mailing lists, and social media communities. Long-time Bitcoin users often approached the halving with a mixture of technical confidence and market fatigue. They remembered previous cycles, exchange failures, fork wars, and the emotional damage of speculative mania. Their discussions frequently centered on node operation, self-custody, fee markets, and the importance of not relying on third parties.
Across forums, the recurring argument was less about short-term price and more about monetary policy: if issuance is fixed, uncertainty must be expressed through valuation rather than supply.
Newer participants, by contrast, were often drawn by macro narratives, technological optimism, or the explosive opportunities in DeFi. Many had never experienced a full bear market and were unfamiliar with the psychological toll of extreme volatility. This created a generational divide between veterans who prioritized survival and newcomers who prioritized opportunity. The result was a rich, sometimes chaotic discourse where technical analysis, monetary theory, smart contract risk, and speculative euphoria coexisted in the same threads.
Early forum reactions also revealed persistent concerns. Bitcoin users debated whether institutional custody undermined the ethos of self-sovereignty. Ethereum users argued about gas fees, centralization risks, and whether yield farming was innovation or speculation. Privacy advocates warned that blockchain transparency could enable surveillance if identities were linked to addresses. These debates were not distractions; they were the living record of a technology trying to define its own values under pressure.
Security Failures and Hard Lessons
2020 was also a year of security incidents that sharpened the industry’s understanding of risk. Flash loan attacks demonstrated that temporary capital could be used to manipulate prices and exploit protocol assumptions within a single transaction. Oracle failures showed that decentralized applications are only as reliable as the data sources they depend on. Admin key compromises reminded users that many supposedly decentralized protocols still contained centralized control points. Exchange hacks reinforced the importance of custody hygiene, multisignature workflows, and operational security.
These events were painful, but they advanced technical practice. Teams began to take formal audits, bug bounties, time locks, governance multisigs, and circuit breakers more seriously. Users became more aware that smart contract risk is not abstract; it is a direct financial exposure. The year helped separate the rhetorical idea of decentralization from the practical engineering required to achieve it. In that sense, the failures of 2020 were as historically important as the successes.
What 2020 Changed in the Historical Record
The history of cryptocurrency and Bitcoin in 2020 is the history of a transition. The market moved from isolated speculation to macro-aware trading. Bitcoin moved from a retail-driven narrative to an institutional scarcity narrative. Ethereum moved from a smart contract platform to a financial settlement layer under real economic load. DeFi moved from experimental contracts to a recognizable, if risky, parallel financial system. Stablecoins moved from trading tools to essential liquidity infrastructure. Regulators moved from peripheral comments to active engagement with custody, payments, and token classification.
Most importantly, 2020 proved that cryptocurrency could no longer be evaluated only as technology. It had to be evaluated as monetary policy, market structure, software risk, governance, and ideology simultaneously. Bitcoin’s fixed supply became more compelling in a world of expanding fiat liquidity. Ethereum’s programmability became more valuable as financial applications gained traction. The cypherpunk dream of permissionless money had not been fully realized, but it had become impossible to dismiss.
By the end of the year, the industry stood at the edge of a new phase. The technical foundations laid before and during 2020 would shape the next cycle: institutional adoption, layer-two scaling, proof-of-stake evolution, regulatory confrontation, and the continuing struggle to build systems that are open, secure, and resilient. 2020 was not the end of cryptocurrency’s early history. It was the moment when that history became inseparable from global finance.
FAQs
What happened to Bitcoin in 2020?
Bitcoin experienced a severe March crash, a third halving in May, and a strong recovery later in the year as institutional interest grew. The network’s issuance rate was cut in half, while market participants increasingly framed Bitcoin as a digital scarcity asset amid global monetary expansion.
When was the 2020 Bitcoin halving?
The third Bitcoin halving occurred at block 630,000 on May 11, 2020. The block reward decreased from 12.5 BTC to 6.25 BTC, reducing the pace of new coin creation and reinforcing Bitcoin’s predetermined supply schedule.
What was DeFi summer?
DeFi summer refers to the rapid growth of decentralized finance protocols in 2020, especially on Ethereum. Lending platforms, automated market makers, liquidity mining, yield farming, and governance tokens attracted massive attention and capital, turning smart contracts into experimental financial infrastructure.
Did Ethereum change in 2020?
Yes. Ethereum launched the Beacon Chain on December 1, 2020, beginning the transition toward proof-of-stake. Phase 0 introduced staking, validators, and slashing mechanics, laying the groundwork for future scalability and consensus upgrades.
Why did March 2020 matter for cryptocurrency?
March 2020 showed that crypto markets were sensitive to global liquidity conditions. Bitcoin fell sharply during the pandemic-driven sell-off, exchanges faced operational strain, and decentralized finance protocols revealed weaknesses in liquidation and oracle design. The crash became a key lesson in market structure and risk management.
Was 2020 the start of institutional crypto adoption?
2020 was a major acceleration point. Public companies, payment firms, custodians, and asset managers became more active in Bitcoin and broader crypto markets. Institutional participation did not replace the original cypherpunk vision, but it changed the market’s structure and narrative.